
Friday, October 30, 2026Oct 30

This story is free to read.

4 alternatives for when your 401(k) doesn’t cut it

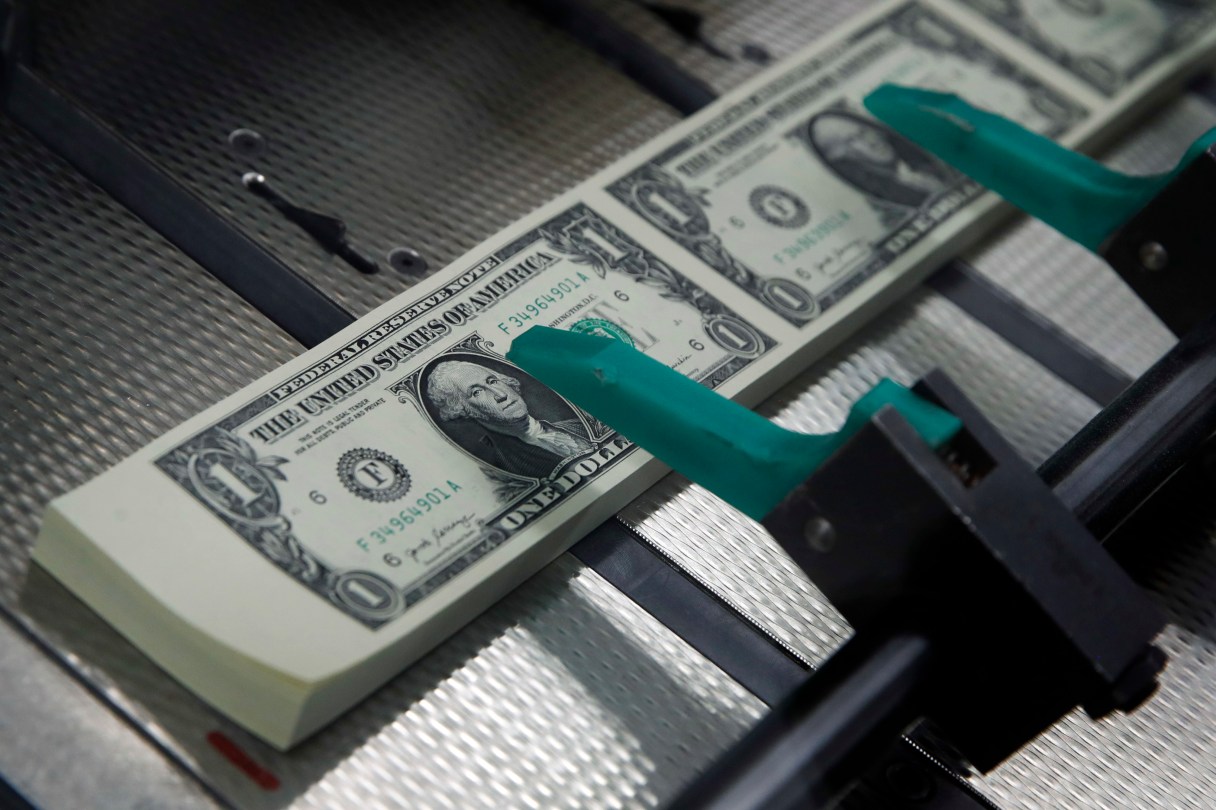
FILE- In this Nov. 15, 2017, file photo, new $1 bills with the signatures of U.S. Treasurer Jovita Carranza and Treasury Secretary Steven Mnuchin are cut and stacked at the Bureau of Engraving and Printing in Washington. There's a finite list of things you can change at work, and your employer's less-than-stellar retirement plan probably isn't among them. An individual retirement account can provide comparable tax benefits to a 401(k), but with a broader array of assets and generally lower associated fees. (AP Photo/Jacquelyn Martin, File)
FILE- In this Nov. 15, 2017, file photo, new $1 bills with the signatures of U.S. Treasurer Jovita Carranza and Treasury Secretary Steven Mnuchin are cut and stacked at the Bureau of Engraving and Printing in Washington. There's a finite list of things you can change at work, and your employer's less-than-stellar retirement plan probably isn't among them. An individual retirement account can provide comparable tax benefits to a 401(k), but with a broader array of assets and generally lower associated fees. (AP Photo/Jacquelyn Martin, File) FILE- In this Nov. 15, 2017, file photo, new $1 bills with the signatures of U.S. Treasurer Jovita Carranza and Treasury Secretary Steven Mnuchin are cut and stacked at the Bureau of Engraving and Printing in Washington. There's a finite list of things you can change at work, and your employer's less-than-stellar retirement plan probably isn't among them. An individual retirement account can provide comparable tax benefits to a 401(k), but with a broader array of assets and generally lower associated fees. (AP Photo/Jacquelyn Martin, File)

There’s a finite list of things you can change at work – and your employer’s less-than-stellar retirement plan probably isn’t among them.

What makes for a lousy 401(k) is somewhat in the eye of the beholder, but characteristics may include limited offerings, high fees or no company match. The following four alternatives can ensure your employer’s retirement plan (or lack thereof) doesn’t derail your plans for retirement.

OPEN AN IRA

An individual retirement account, either of the Roth or traditional variety, can help solve for an employer-sponsored plan plagued by lackluster options and high fees. An IRA provides comparable tax benefits to a 401(k), but with a broader array of assets and generally lower associated fees.

Take exchange-traded funds, for example. These darlings of the investment world still aren’t offered in a majority of 401(k) plans, according to data from the Investment Company Institute, a trade group. With an IRA, you’ll gain access to ETFs, along with stocks, options and bonds; meanwhile, most employer-sponsored plans are confined to mutual or index funds.