
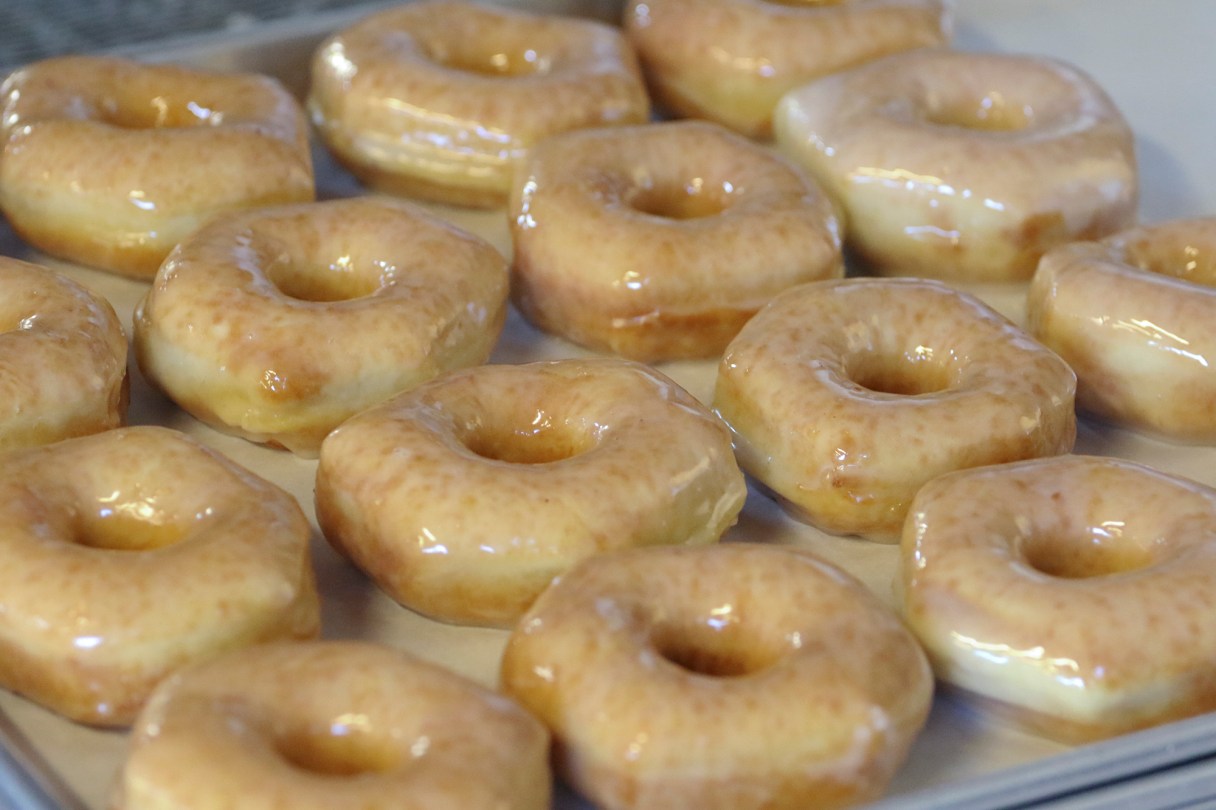
Salvation Army gives donuts to police, firemen
The Chattanooga Salvation Army will celebrate the 81st Annual National Donut Day today by delivering donuts to local fire, police, city officials and armed forces units. In addition, Tasty Donuts will celebrate with all employees dressed as “Donut Lassies” and will give each customer a free donut and collect donations for The Salvation Army.
National Donut Day was established in 1938 to honor “Donut Lassies,” female Salvation Army volunteers who prepared donuts for servicemen during World War I. By frying donuts for soldiers on the front lines, those volunteers were able to remind the soldiers of home.
Donut deliveries will begin at 10 a.m. today from The Salvation Army at 822 McCallie Ave.
Customers can enjoy a free donut from Tasty Donuts and make a donation in the counter top Red Kettles. All proceeds benefit The Salvation Army.
“We are grateful for loyal partners like Tasty Donuts, who have proven to be exceptional in their efforts to join us in doing the most good,” said Major Robert Lyle, area commander for The Salvation Army of Greater Chattanooga.
CBL keeps dividend despite lower stock price
CBL & Associates Properties said Thursday it is keeping its dividend rate despite the drop in the company’s stock price over the past year.
The Chattanooga-based real estate developer said it will pay a quarterly dividend of 20 cents per share, in line with previous dividends, on July 16 to shareholders of record on July 2.
At the company’s current share price, that equates to a forward yield of 15.81 pecent.
Shares of CBL stock closed Thursday at $5.06 per share, which is 26.5 percent below its price of $6.88 per share a year ago.
Waymo uses minivans for self-driving service
A self-driving car service that Google spinoff Waymo plans to launch later this year in Arizona will include up to 62,000 Chrysler Pacifica Hybrid minivans.
The deal announced Thursday is the latest sign of Waymo’s confidence in its self-driving car technology, which sprang from a secret Google project started nine years ago. The technology will be deployed in a ride-hailing service in the Phoenix area before the end of this year and then expand into other U.S. markets.
Waymo plans to pick up people in cars that won’t have a human in the driver’s seat, making it the first ride-hailing service with a fleet of fully autonomous vehicles.
The company already had bought 600 Pacifica Hybrid minivans from Fiat Chrysler with a commitment to add “thousands” more. Waymo and Fiat also are discussing other ways to expand their partnership, including possibly striking a deal to sell Chrysler vehicles with self-driving technology to consumers.
Mortgage rates fall after 7 years of rises
Long-term U.S. mortgage rates fell this week, breaking a steady climb that pushed them to their highest levels in seven years.
It was the first decline in four weeks in long-term loan rates amid the peak home buying season. Mortgage buyer Freddie Mac said Thursday the average rate on 30-year, fixed-rate mortgages was 4.56 percent, down from 4.66 percent last week. The average benchmark rate has been running at its highest levels since May 2011. By contrast, the 30-year rate averaged 3.94 percent a year ago.
The average rate on 15-year, fixed-rate loans dipped to 4.06 percent from 4.15 percent last week.
The average doesn’t include extra fees, known as points, which most borrowers must pay to get the lowest rates. The fees on 30-year and 15-year fixed-rate mortgages were both unchanged at 0.4 percent.
The average rate for five-year adjustable-rate mortgages fell to 3.80 percent from 3.87 percent last week. The fee remained at 0.3 percent.
Consumer spending best in five months
Americans boosted their spending by 0.6 percent in April, the biggest increase in five months and a strong indication that the economy is reviving after a winter slowdown.
The Commerce Department said Thursday that last month’s increase in consumer spending was the largest increase since an 0.7 percent rise last November.
The better-than-expected April gain, which followed a strong 0.5 percent March increase, caused some economists to boost expectations for economic growth, as measured by the gross domestic product, in the April-June quarter.
“The first two months of the year were downers on the consumer spending front, but spending came back to life in March and April despite rising gasoline pump prices,” said Chris G. Christopher Jr., senior economist at IHS Market.
He said his forecast for second quarter economic growth, is now at 4 percent. That would be the strongest quarterly growth in four years and a significant rebound from a modest 2.3 percent gain in the first quarter.
An inflation measure closely watched by the Fed rose by 2 percent in April, compared with a year ago, the second month it has achieved the Fed’s target for inflation after years of chronically low inflation.
The Fed seeks to manage the economy to achieve moderate annual gains in inflation of around 2 percent. However, for the past six years it has failed to achieve that goal as the fallout from the country’s worst recession in seven decades depressed wages and made it hard for businesses to raise prices.
Home sales fall 1.3 percent in April
Fewer Americans signed contracts to buy homes in April, reflecting the dearth of properties being listed for sale in the U.S. right now.
The National Association of Realtors said Thursday that its pending home sales index fell 1.3 percent in April to 106.4, after rising for two consecutive months. The index has drifted downward 2.1 percent from a year ago as the housing shortage has grown more intense. The association reported previously that sales listings in April had declined 6.3 percent over the past 12 months.
A relatively robust job market has led more Americans to look for homes. But the housing shortage and rising mortgage rates over the past year are putting home ownership out of reach for an increasingly large number of people.
Home prices are rising at more than double the gains in average hourly earnings, meaning that many first-time buyers are being forced into lower down payments to afford a home. The S&P CoreLogic Case-Shiller 20-city home price index released this week climbed 6.8 percent in March from a year earlier.