
Biggest banks in Chattanooga
In the six-county Chattanooga metropolitan area, 27 banks collectively had more than $9 billion on deposit last year. The largest commercial banks, as measured by deposits as of June 30, 2015, were:1. First Tennessee, $2.1 billion in deposits at 20 offices.2. SunTrust, $1.75 billion in deposits at 25 offices.3. Regions, $1.18 billion in deposits at 22 offices.4. Pinnacle (formerly CapitalMark), $594.7 million at a single office.5. First Volunteer, $427 million at 11 offices.6. Bank of America, $338 million at four offices.7. Smart Bank (formerly Cornerstone), $331.9 million at five offices.8. FirstBank (acquired Northwest Georgia Bank)*, $330.7 million at eight offices.9. FSG Bank, $316.1 million at seven offices.10. Citizens Tri-County, $295. million at nine offices.* Total of FirstBank and Northwest Georgia in the marketSource: Federal Deposit Insurance Corp.Pruning branchesAlthough bank deposits have continued to grow in the Chattanooga area, the total number of branches has declined by 21 branches from the peak in 2008.Year No. of bank branches2015 – 1582014 – 1612013 – 1662012 -1732011 – 1752010 – 1752009 – 1782008 – 1792007 – 1752006 – 167Source: Federal Deposit Insurance Corp.
Historically, the biggest reason why people picked a bank to deposit money or write checks was the convenience and location of its branches. But in today’s digital, 24-7 world of e-commerce, automatic teller machines or mobile phones have replaced tellers and even lending officers at conventional bank offices for a growing number of consumers.
Bankrate.com estimates more than 40 percent of Americans haven’t visited a bank branch in the past six months. In the future, experts expect even more people will be doing their banking online, on their phone or at ATMs.
Chattanooga banks are pruning their branch networks even as deposits and loans continue to grow. Since 2008, the total number of bank branches in metropolitan Chattanooga has fallen by nearly 12 percent while overall bank deposits have grown by more than 18 percent, or nearly $1.5 billion.
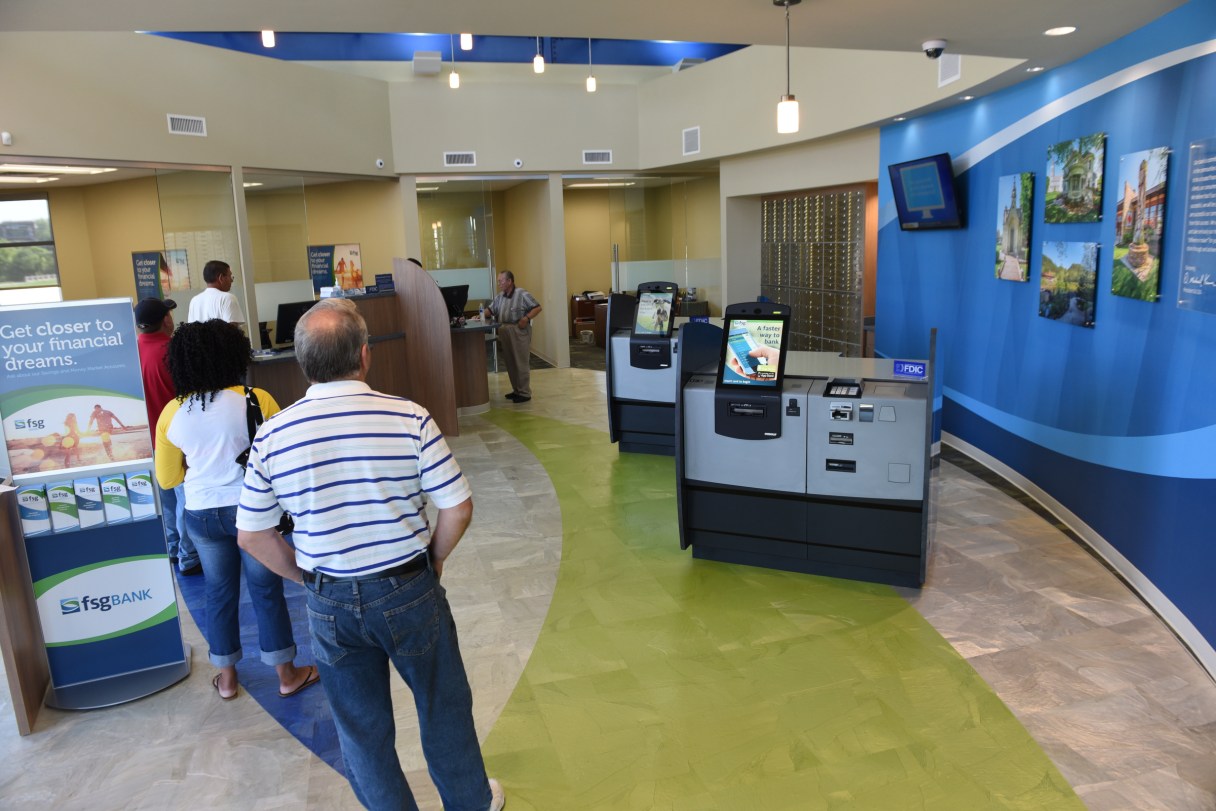
“People want to engage with technology – they want the consistency and speed,” says Mike Kramer, CEO of FSG Bank, which has closed or sold nearly half of the 36 branches it once operated across East and Middle Tennessee and Northwest Georgia. “One of the traps is trying to be all things for all people. We’ve tried to narrow our focus to concentrate on offering the very best services and products for small to mid-sized businesses, their managers and the employees.”
In Cleveland, FSG combined two traditional branches into a new office model where customers can easily handle more of their routine business on machines. Meanwhile, human tellers and loan officers have become “universal bankers” ready to handle a variety of financial services.
Technology has allowed First Tennessee to grow into Chattanooga’s biggest bank while cutting its staff nearly in half since it entered the Chattanooga market four decades ago. First Tennessee cut its branch network in Chattanooga by a couple of offices over the past decade and sold its 16-story headquarters building in downtown Chattanooga last year for $14 million. The bank continues to lease three floors of its headquarters building downtown, but First Tennessee is continuing to sell some of its offices across the state, including its 25-story headquarters building now up for sale in Memphis.
Still, Jeff Jackson, the market president for First Tennessee in Chattanooga, said branches and their staff remain key to the banking business even though fewer customers are visiting branches for routine transactions.
“We’ve built a strong reputation based on relationships that have been nurtured over generations of customers,” Jackson says. “Our strength begins with our team members at each one of our 25 branches and continues with the hours they volunteer each year and the expertise they share so generously.”
Jackson said his goal when he was named this year to head First Tennessee operations in Chattanooga was to keep the bank’s top position in the market “and to continue to grow our footprint.” That growth doesn’t necessary mean more offices like in the past, Jackson said. Staffers are trained to handle a variety of financial services that the consumer may need.
“We’re trying to be a one-stop job for everything for the consumers’ personal, commercial and wealth management needs – all things financial,” he says.
A Federal Deposit Insurance Corp. report last year found that visiting a teller still remains the most common way for people to access their account. But having the most branches doesn’t guarantee more business. CapitalMark Bank, which was started in 2007 from a single office in Chattanooga, grew to nearly $1 billion in assets in less than a decade with only four offices in East Tennessee. Last year, CapitalMark was acquired by Pinnacle Bank in Nashville, the state’s fastest growing bank, and took on the Pinnacle name in Chattanooga in March.
Pinnacle plans to add a second Chattanooga branch at Shallowford and Shepherd roads later this year and expects to add a new branch in each of the next five years to become one of Chattanooga’s biggest banks.
“Our model served us well here in Chattanooga to grow as we did as Chattanooga’s fastest growing bank with just a single office,” says Craig Holley, the former CEO of CapitalMark who now serves as the market chairman for Pinnacle in Chattanooga. “But as we move forward, we’re going to find some strategic locations around town where we can pick up additional business in the market with some additional branches.”
As mobile services expand, banks will be looking for more ways to integrate banking on a phone with banking in a branch.
“Online banking will continue to grow, but banking is still a relationship business,” said Jim “JV” Vaughn, the market president for SunTrust Banks in Chattanooga. “We working to meet all of the financial needs for our customers.”
Vaughn and other bankers said loan demand is growing in 2016 and banks are still eager to lend money, albeit with a bit more caution than they were prior to the Great Recession and the Dodd-Frank regulations Congress enacted after the 2008-2009 banking crisis.
Smart Bank, which merged with the former Cornerstone Bank in Chattanooga last year, is adding mortgage lending to its portfolio of services to help the East Tennessee bank grow its presence in the market and tap into the growing demand for home loans.
But with an improving economy, banks are still battling headwinds from both government regulators and alternative private sector financiers. The Internet has given borrowers greater access to alternative financing methods, from Kickstarter to Kabbage, and allowed online lenders and deposit-gathering institutions to serve customers almost anywhere with or without a local presence.
As a result, fewer new banks are being started and more are combining to achieve economies of scale, especially with regulations that require banks to have more compliance officers and oversight. As a result, the number of banks operating across Tennessee declined by nearly 10 percent in the past decade to 214 as of June 30, 2015. That number is down early 20 percent from the levels of 20 years ago.
“Regulations are definitely raising the costs of compliance, especially for many community banks,” says Colin Barrett, president of the Tennessee Bankers Association. “The banking market in Tennessee is healthy, but we’re not seeing new bank startups or new offices being added like we saw in the past.”
Nationwide, the number of U.S. banks has dropped by nearly two-thirds from the height 20 years ago of more than 18,000 banks.
But Mike Sarvis, president of Cohutta Banking Co. in Chattanooga, which added to its local branch network over the past decade, insists that banking is still a relationship business.
“Personal relationships and customer service are still vital in providing the right financial services for each individual,” said Mike Sarvis, president of Cohutta Banking Co. in Chattanooga. “Even with as many banks as there are in the market, we still see opportunities for growth.”