
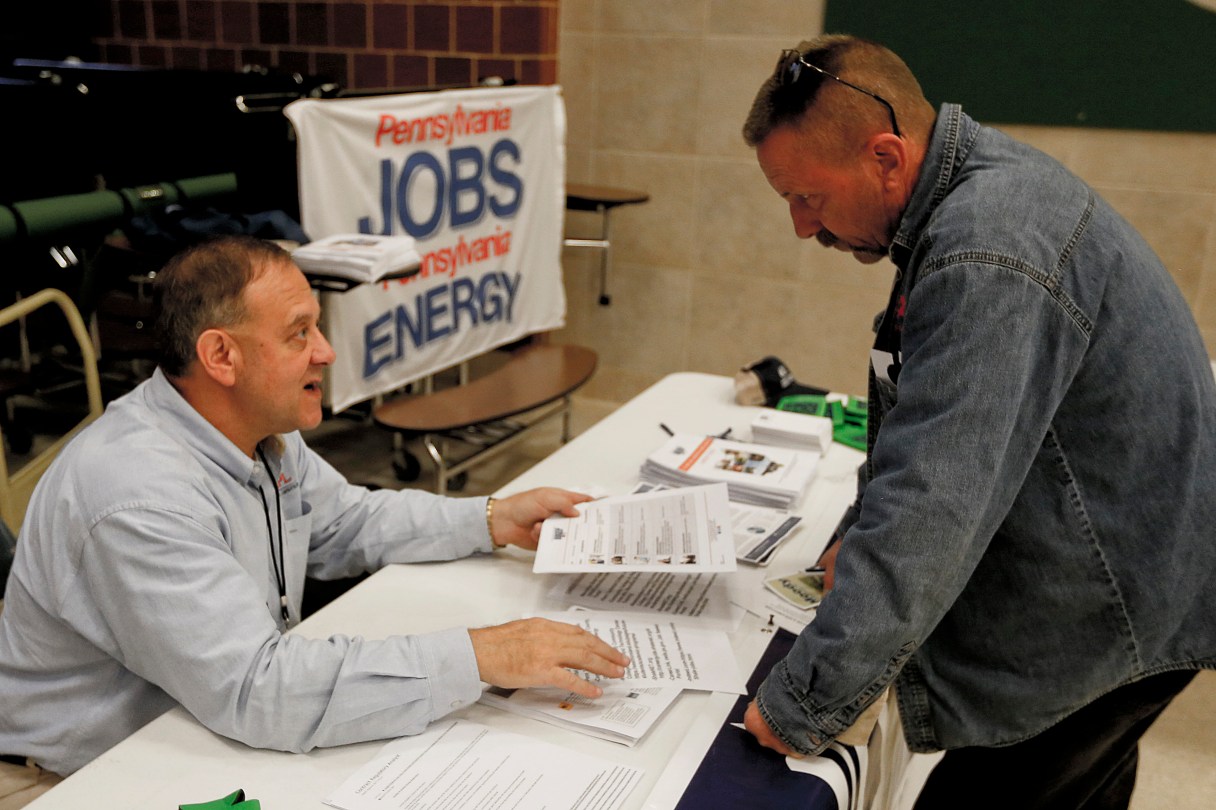
U.S. businesses added 163,000 jobs in August, a private survey found, a decent gain that suggests that employers are confident enough to keep hiring.
Payroll processor ADP said Thursday that the job gains were the fewest since October. But last month’s pace of hiring is still enough to lower the unemployment rate over time.
ADP’s hiring figures came a day before the government will release its official jobs data for August. Economists have forecast that Friday’s report will show that employers added a solid 189,000 jobs last month, according to data provider FactSet.
The job gains ADP reported for August were much lower than the 217,000 that it said were added in July. Hiring by small businesses – defined as those with fewer than 50 employees – remained sluggish last month and depressed overall job growth.
Mark Zandi, chief economist at Moody’s Analytics, said that with the unemployment rate at a low 3.9 percent, smaller companies are having a harder time finding workers. Larger firms are typically able to offer high pay or more benefits and can pull in more employees as a result.
Mortgage rates rise to seven-year high
Long-term U.S. mortgage rates ticked up this week for the second straight week, remaining substantially higher than a year ago amid strength in the economy.
Mortgage buyer Freddie Mac said Thursday the average rate on 30-year, fixed-rate mortgages rose to 4.54 percent from 4.52 percent last week. Long-term loan rates have been running at their highest levels in seven years. The average benchmark 30-year rate reached a high this year of 4.66 percent on May 24. By contrast, the rate stood at 3.78 percent a year ago.
The average rate on 15-year, fixed-rate loans edged up to 3.99 percent this week from 3.97 percent last week.
Home borrowing costs “may be slowly on the rise again in coming weeks,” said Freddie Mac chief economist Sam Khater. He said the lack of affordable homes “is hindering many interested buyers this fall, even as the robust economy brings them into the market.”
To calculate average mortgage rates, Freddie Mac surveys lenders across the country between Monday and Wednesday each week. The average doesn’t include extra fees, known as points, which most borrowers must pay to get the lowest rates.
The average rate for five-year adjustable-rate mortgages jumped to 3.93 percent from 3.85 percent last week.
Twitter bans Infowars for Jones’ behavior
Twitter is permanently banning right-wing conspiracy theorist Alex Jones and his “Infowars” show for abusive behavior.
The company said Jones won’t be able to create new accounts on Twitter or take over any existing ones. Twitter said Jones posted a video on Wednesday that violates the company’s policy against “abusive behavior.”
The video in question showed Jones shouting at and berating CNN journalist Oliver Darcy for some 10 minutes in between two congressional hearings focused on social media. Twitter CEO Jack Dorsey testified at both hearings, but did not appear to witness the confrontation.
Jones had about 900,000 followers on Twitter. “Infowars” had about 430,000.
Twitter had previously suspended Jones for a week. But until now it had resisted muzzling Jones further. Other tech companies have limited Jones by suspending him for longer periods, as Facebook did, and by taking down his pages and radio stations.
In Chattanooga, NoogaRadio (92.7 FM and 95.3 HD4) continues to air Alex Jones, which the station says is “fighting for the American way against tyranny.”
Wells Fargo probed for fraud, report says
The Justice Department is investigating potential employee fraud at Wells Fargo & Co.’s wholesale banking unit, according to the Wall Street Journal.
Citing unnamed people familiar with the probe, the Journal reported Thursday that investigators are trying to determine whether management at the bank pressured employees to improperly alter customer information without consent. The investigation stems from revelations that employees in the wholesale banking unit, which caters to corporate customers, added Social Security numbers, dates of birth and other customer information to documents in a bid to beat a regulatory deadline.
The matter initially involved Well’s business banking group, which focuses on companies with annual sales of $5 million to $20 million, but further reviews by the bank discovered that the problems were more widespread, according to the Journal’s report.
Wells Fargo spokesman Alan Elias said the matter involved a new process and a new required document that the bank’s employees had to complete “to help ensure we know our customers.”