
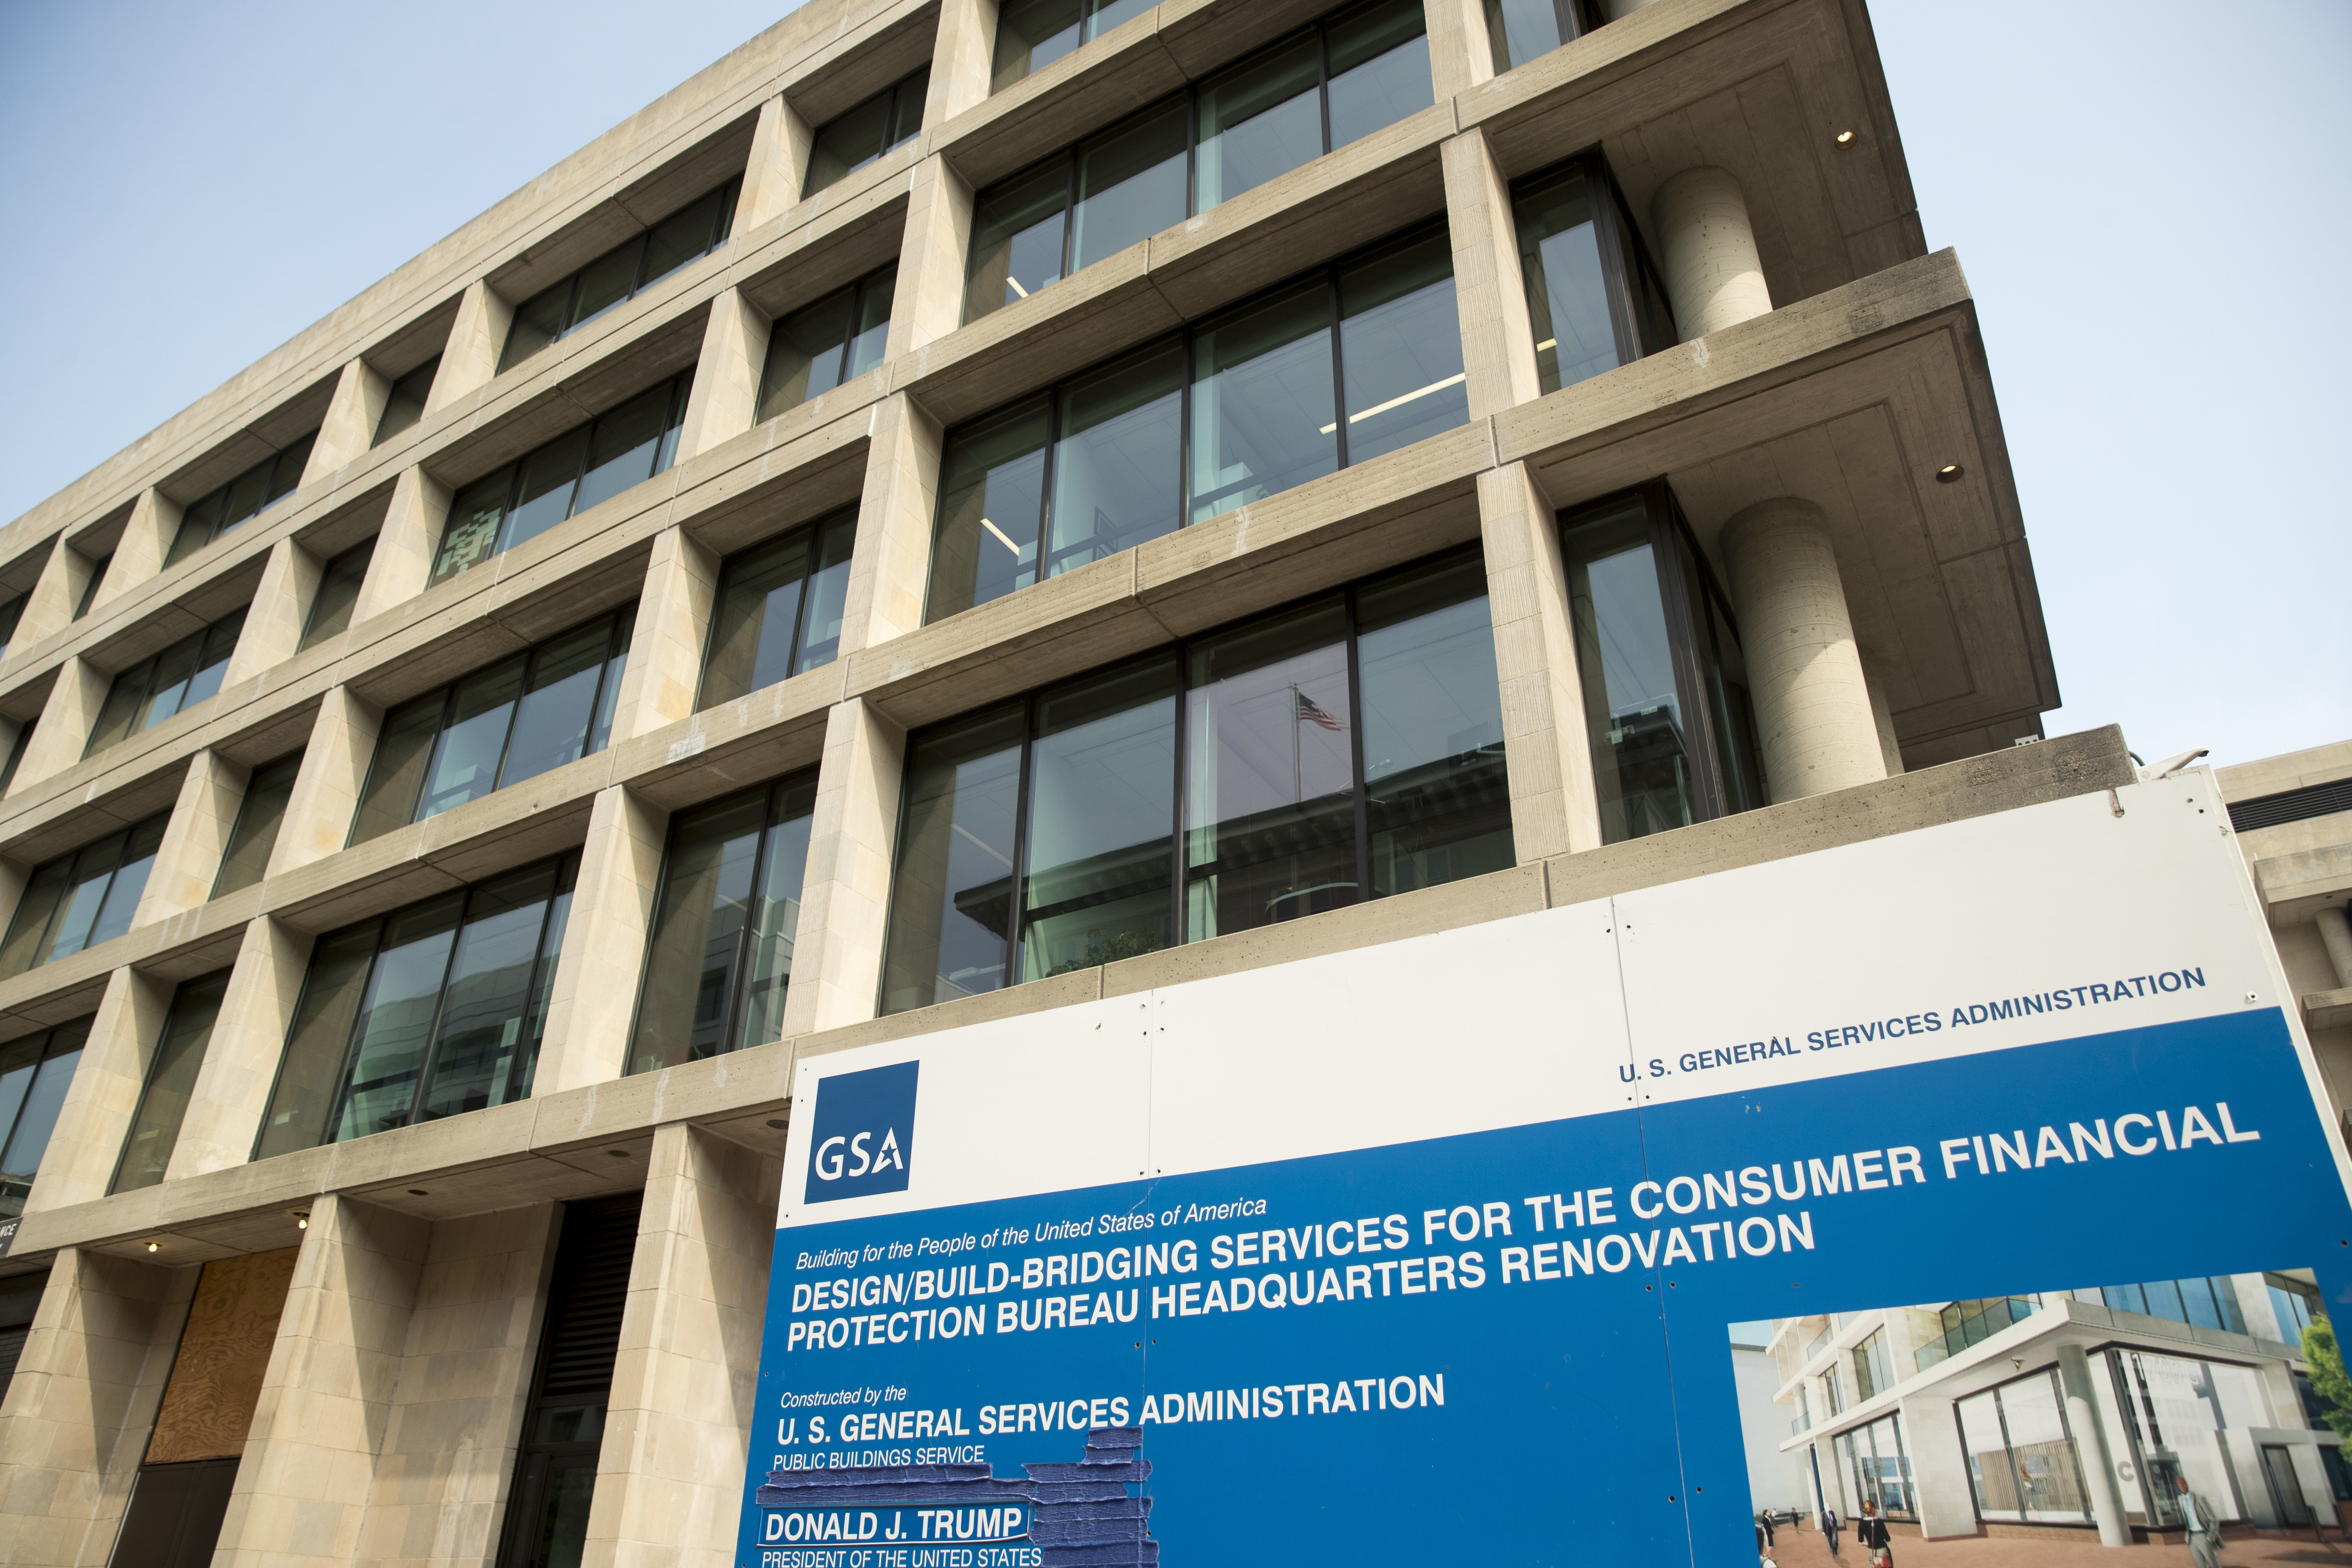
 FILE- In this Aug. 27, 2018, file photo a sign stands at the construction site for the Consumer Financial Protection Bureau’s new headquarters in Washington. The nation’s federal financial watchdog has announced its plans to roll back most of its consumer protections governing the payday lending industry. It’s the Consumer Financial Protection Bureau’s first rollback of regulations under its new Director, Kathy Kraninger, who took over the bureau late last year. (AP Photo/Andrew Harnik, File)
The nation’s federal financial watchdog plans to abolish some of its most critical consumer protections governing payday lenders.
The move is a major win for the payday lending industry, which argued the government’s regulations could kill off a large chunk of its business. It’s also a big loss for consumer groups, who say payday lenders exploit the poor and disadvantaged with loans that have annual interest rates as much as 400 percent.
The cornerstone of the regulations was a requirement that lenders make sure borrowers could afford to repay a payday loan without being stuck in a cycle of debt, a standard known as “ability to repay.” That standard would be eliminated under the new rules. Another part of the rules, which would have limited the number of payday loans a person could roll over, was also eliminated.
Critics of the payday lending industry have argued that without these underwriting standards, the CFPB’s new regulations are effectively toothless. The main criticism of the payday lending industry was that many borrowers would take months to repay a loan that was originally designed only to last a couple of weeks, renewing the loan over and over again.
“This proposal is not a tweak to the existing rule it’s a complete dismantling of the consumer protections [the bureau] finalized in 2017,” said Alex Horowitz, a researcher with Pew Charitable Trusts, a think tank whose research on the industry was relied on heavily by the bureau when the original rules were unveiled a year and a half ago.