
 Joe Jansen, a YMCA employee, sits for a photo outside his workplace Tuesday in Chattanooga. Jansen turns 26 in November and will no longer be eligible to remain on his parents’ health insurance.
 Ashley Mitchell-Patrick works in her Cleveland, Tenn., shop Friday morning.
 Ashley Mitchell-Patrick works in her Cleveland, Tenn., shop Friday morning.
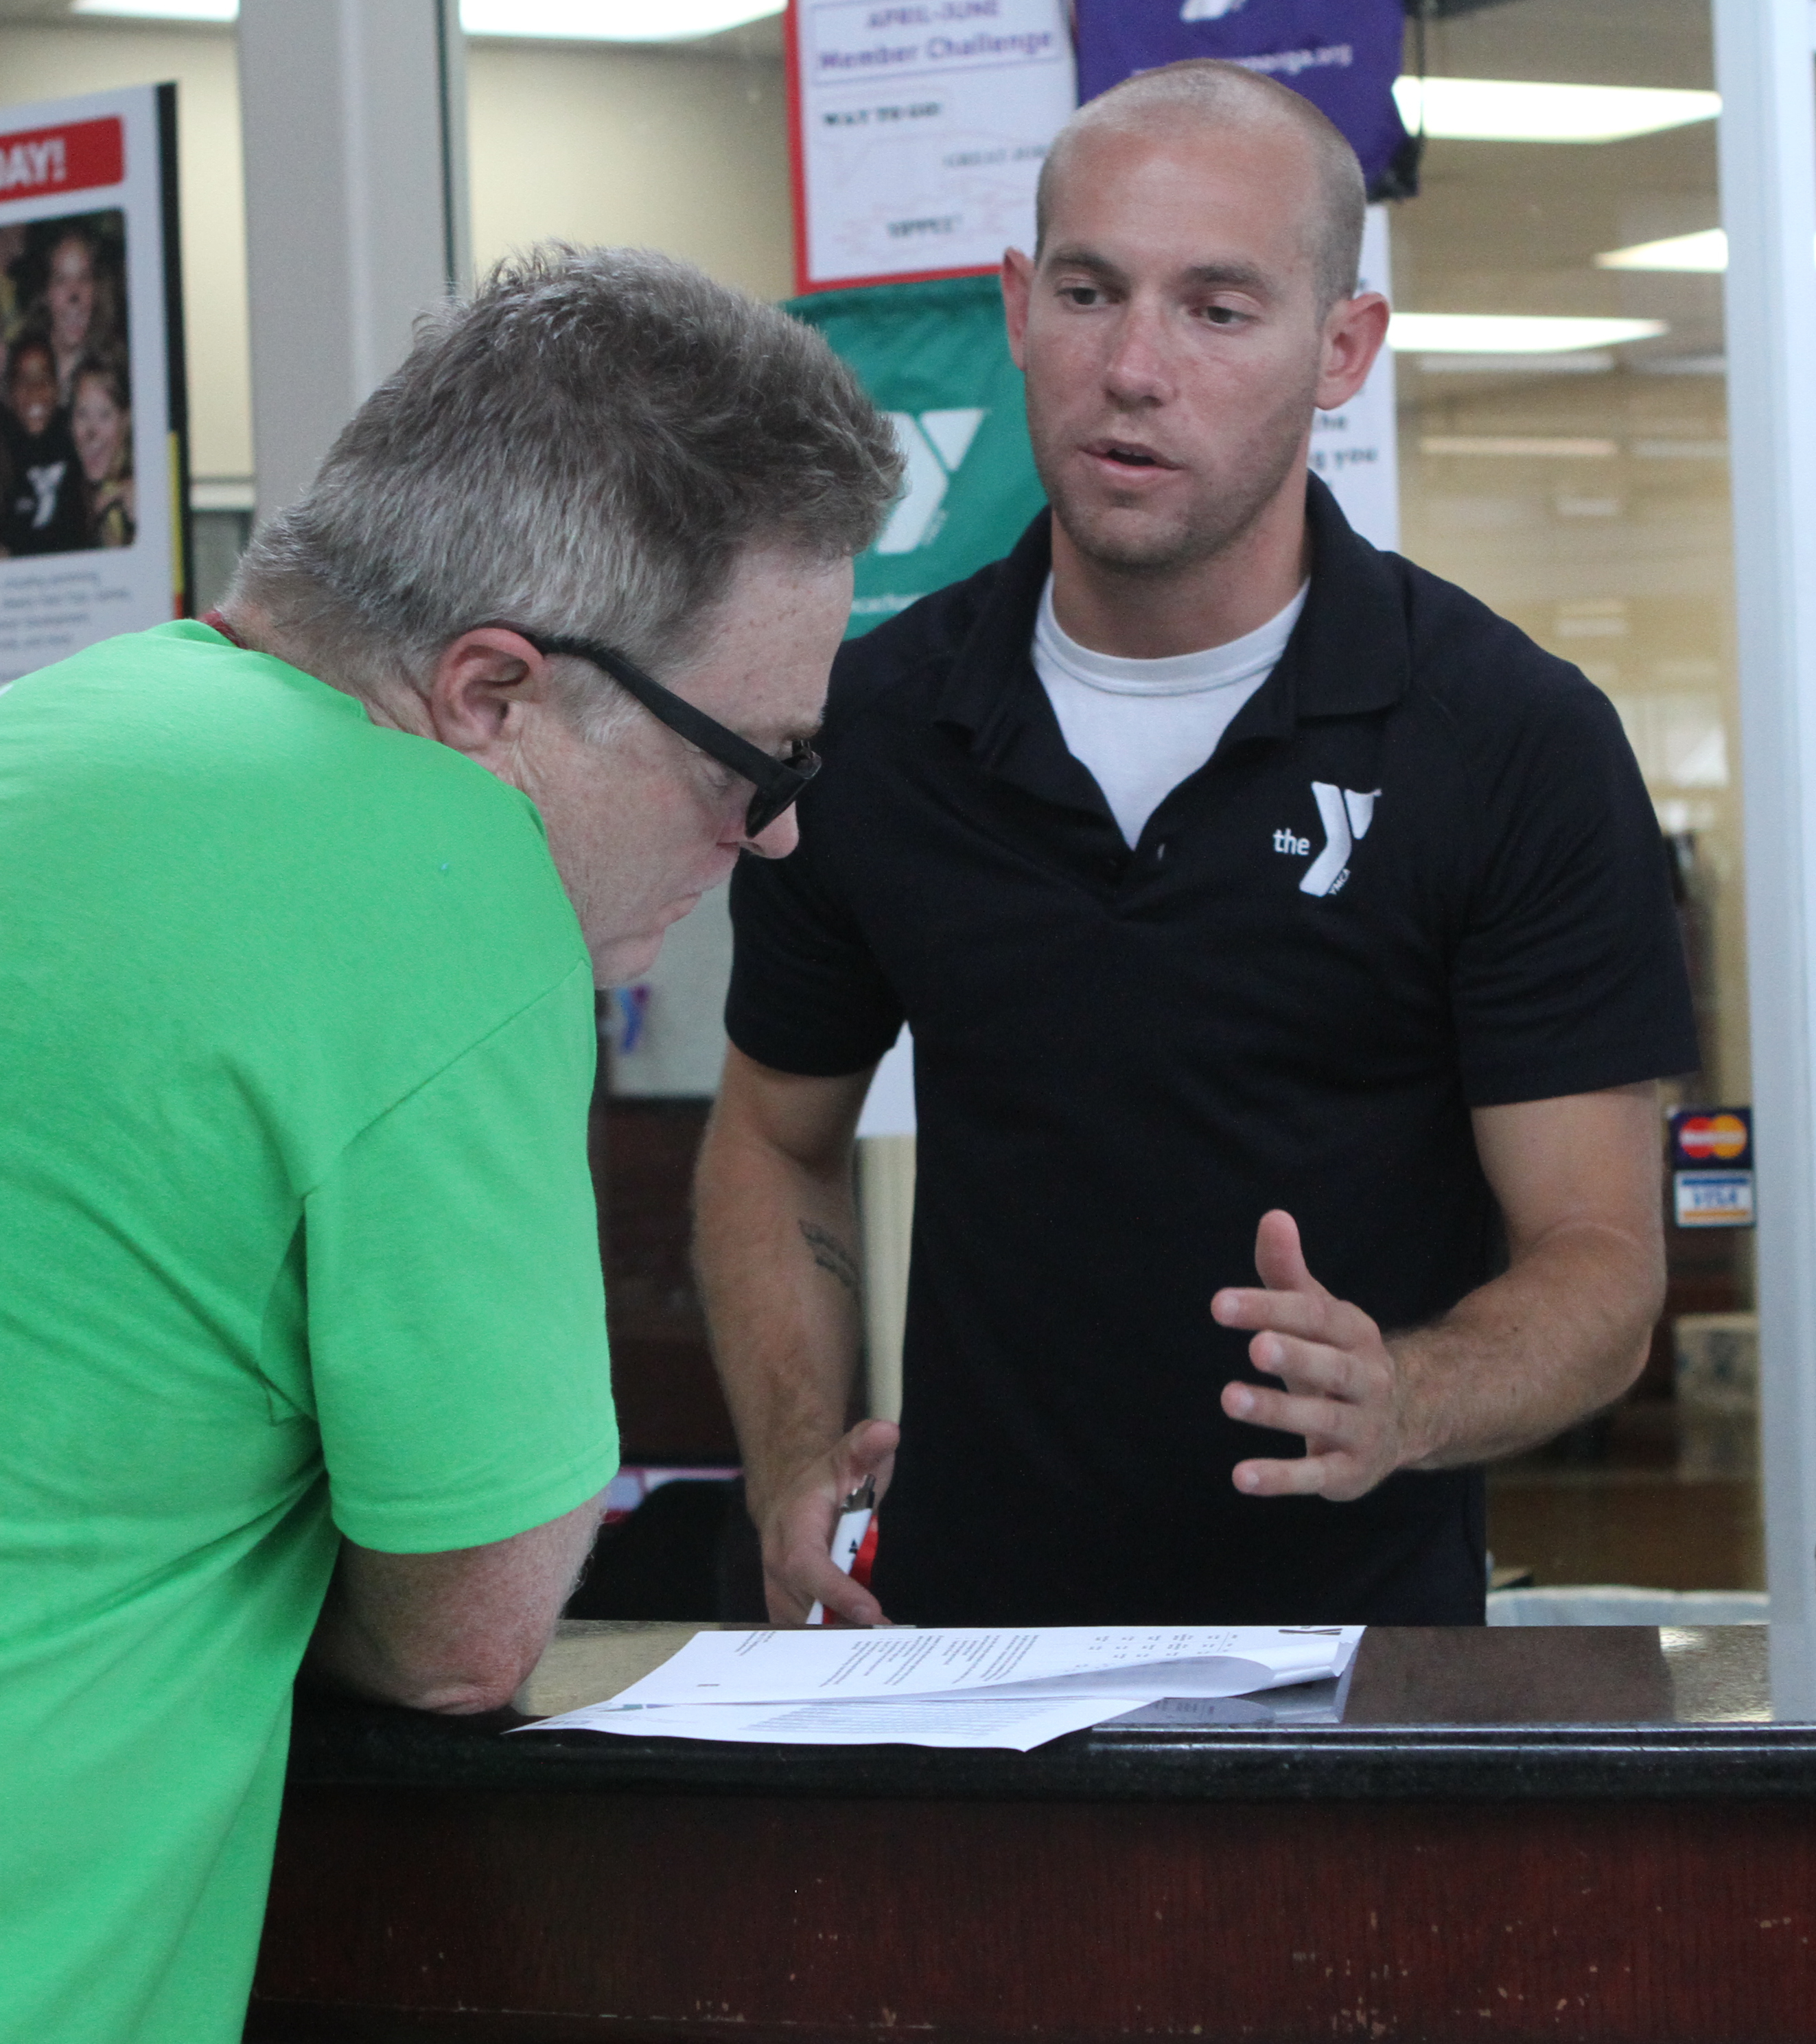 Joe Jansen, a Chattanooga YMCA employee, talks to Bill Thurman, a truck driver, about gym membership options on Tuesday. Jansen turns 26 in November and will no longer be eligible to remain on his parents’ health insurance.
LEARN MORE*Federal informational site: HealthCare.gov*BlueCross BlueShield’s educational site: bcbst.com/knownow*Cigna’s educational site: informedonreform.com*American Exchange: http://americanexchange.com/*Kaiser Family Foundation: http://kff.org/health-reform/FAST FACTS* HEALTH INSURANCE MARKETPLACES: Public Health Insurance Marketplaces will be a new online portal to compare the costs of various health plans, and potentially receive tax credits to put towards buying such plans. Tennessee will have a federally facilitated marketplace. http://marketplace.cms.gov/* TAX SUBSIDIES: People with incomes between 100 percent and 400 percent of the poverty rate who purchase coverage through a health insurance exchange may be eligible for a range of tax subsidies, which will be delivered in the form of both advanceable and refundable tax credits.* TIERED RATES: Marketplace insurance plans are put into 4 categories based on how you and the plan can expect to share the costs of care: Bronze, silver, gold and platinum. The category you choose affects how much your premium costs each month and what portion of the bill you pay for things like hospital visits or prescription medications. It also affects your total out-of-pocket costs. All marketplace insurance plan categories must offer the same set of essential health benefit. The marketplace also offers “catastrophic” plans to people under 30 years old and to some people with very low incomes.* TYPES OF PLANS: The marketplace opens the door to plans offered by private companies, and also tells you if you qualify for free or low-cost coverage available through Medicaid or the Children’s Health Insurance Program (CHIP). The government regulates what kinds of features need to be included in private plans, and sets thresholds for costs. The government also is in charge of the tax subsidies. So far, BlueCross BlueShield of Tennessee, Cigna, Humana, Coventry Health & Life and Community Health Alliance have submitted plans to the marketplace.* PENALTIES FOR NOT BUYING INSURANCE: In 2014, the penalty will be $95 per adult and $47.50 per child (up to $285 for a family) or 1 percent of family income. The next year, it will triple.* TIMELINE: Open enrollment runs from Oct. 1, 2013, to March 31, 2014. Coverage through plans purchased on the exchanges starts Jan. 1 2014.Sources: HealthCare.gov, Kaiser Family Foundation, Tennessee Healthcare Finance and Administration
When Joe Jansen blows out the candles on his 26th birthday cake this November, it may be a good moment to wish for a job with health benefits.
Ever since the Affordable Care Act extended the time young adults could stay on their parents’ health insurance, the 26th birthday has become a new, somewhat unpleasant rite of passage for those who depended on the extra time to find footing in a recession-addled job market.
Jansen is a full-time student at Chattanooga State Community College. His part-time job selling memberships at the YMCA doesn’t include health benefits.
Before the health law, he spent some time uninsured, and for a while he paid for a high-deductible individual plan. But after the law was passed in 2010, his mother suggested he rejoin the family’s plan. It dramatically reduced his co-pays, allowed him to get ACL surgery and freed him to finish school.