
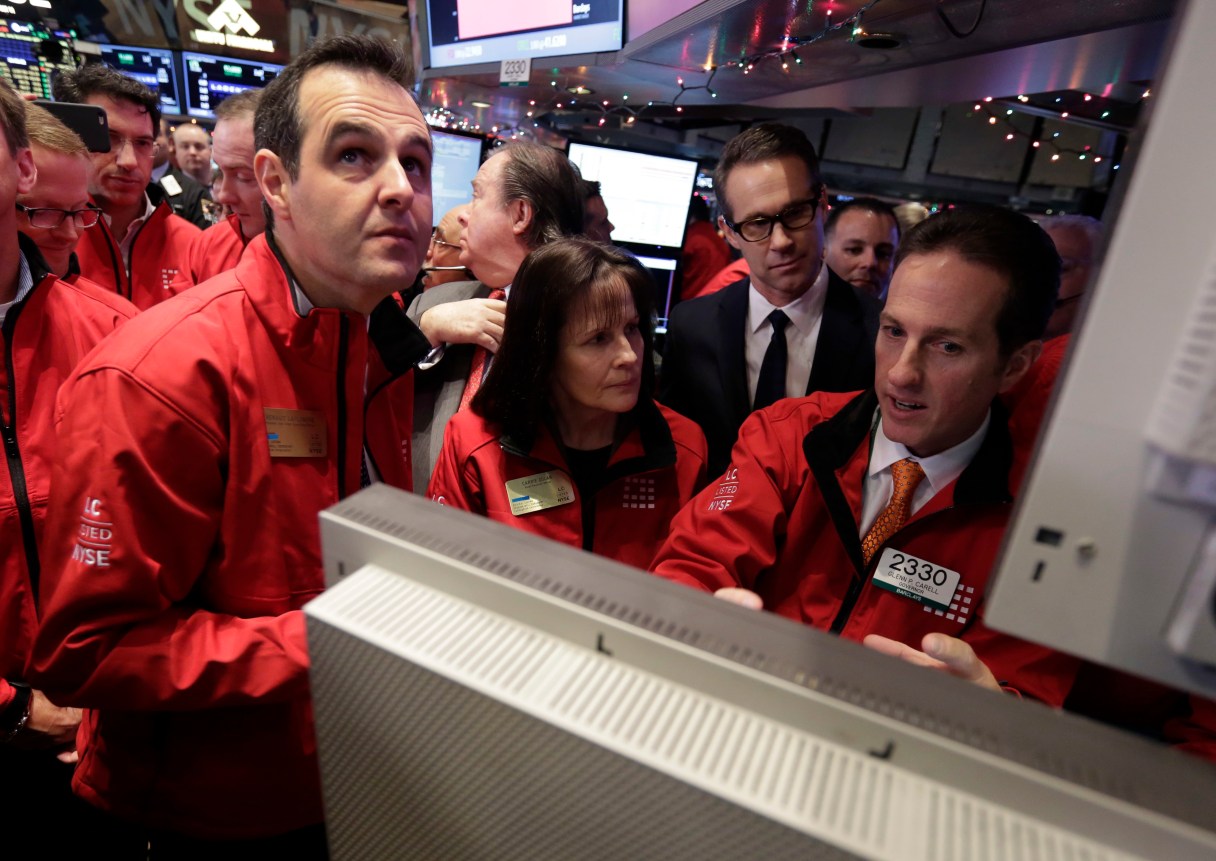
NEW YORK (AP) – Shares of LendingClub, which forced out its founder last week, slumped in early trading after the U.S. Department of Justice opened an investigation and the company raised fresh concerns about funding.
Despite a letter sent to investors Tuesday detailing new measures to strengthen internal controls, shares fell 6 percent. Shares have plunged 50 percent in the past month.
The San Francisco company said late Monday that “it likely may need to use a greater amount of its own capital to purchase loans on its platform compared to prior periods.”
LendingClub is a peer-to-peer lender, meaning it matches people and businesses that need loans with those who want to provide them.
The idea, touted as a super-efficient method of getting capital where it’s needed, was welcomed avidly by investors who sent the company’s market capitalization soaring into the billions shortly after it became public in late 2014. But Wall Street has cooled since then and in the past year, company shares have fallen 80 percent.