
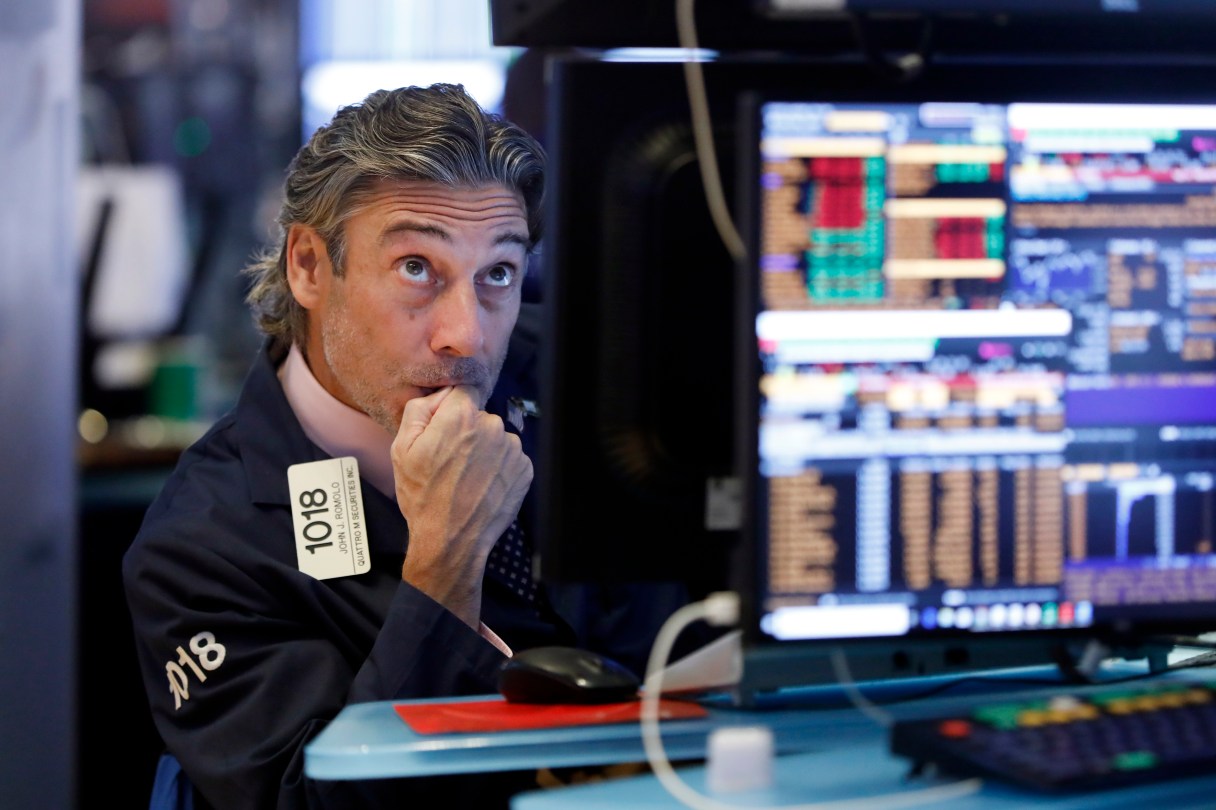
Imagine heading off to work, knowing the stock market was likely to open higher. On the commute, you hear that a salvo of tweets has caused the Dow to sink 600 points and your 401(k) to lose 2% (well, it could happen). If you sigh quietly and switch the station to Easy Listening, this column is not for you.
If, however, you log into your account four times before lunch, then you may need to step back and assess the risk in your portfolio. All investments involve some degree of risk. The key to success is taking action to understand it and to find the level with which you are comfortable. This is easier said than done, and many investors learn too late that their appetite for risk is actually lower than their allocation reflects.
Let’s begin with a definition. In modern financial theory, risk has a fairly precise meaning: the standard deviation of returns over some period of time. Not exactly helpful for most of us trying to get through to retirement. This mathematical definition of “risk” is really a measure of the uncertainty of expected returns, or more descriptively the volatility, both upward and downward. But individuals are most concerned about downside disappointments; we don’t think of above-average returns in terms of risk.
A more useful (and intuitive) construct for retirement savers is the likelihood of losing money. Every member of the investment universe carries some possibility of loss. Even “risk-free” assets like U.S. Treasury Bonds can decline in value when interest rates rise, while investments in highly speculative companies or asset classes (Bitcoin anyone?) can realize substantial declines or even go to zero. The object is to understand the level or risk you are taking on before you actually face the test.
 Christopher A. Hopkins
Risk is attenuated by diversification: blending investments of varying degrees of volatility to arrive at an aggregated collection that is conducive to a good night’s sleep. Actually constructing the finished portfolio, especially in a 401(k) with limited investment options, is relatively straightforward with the tools available in most plans. Assessing the risk with which you are at ease can be the harder part.