
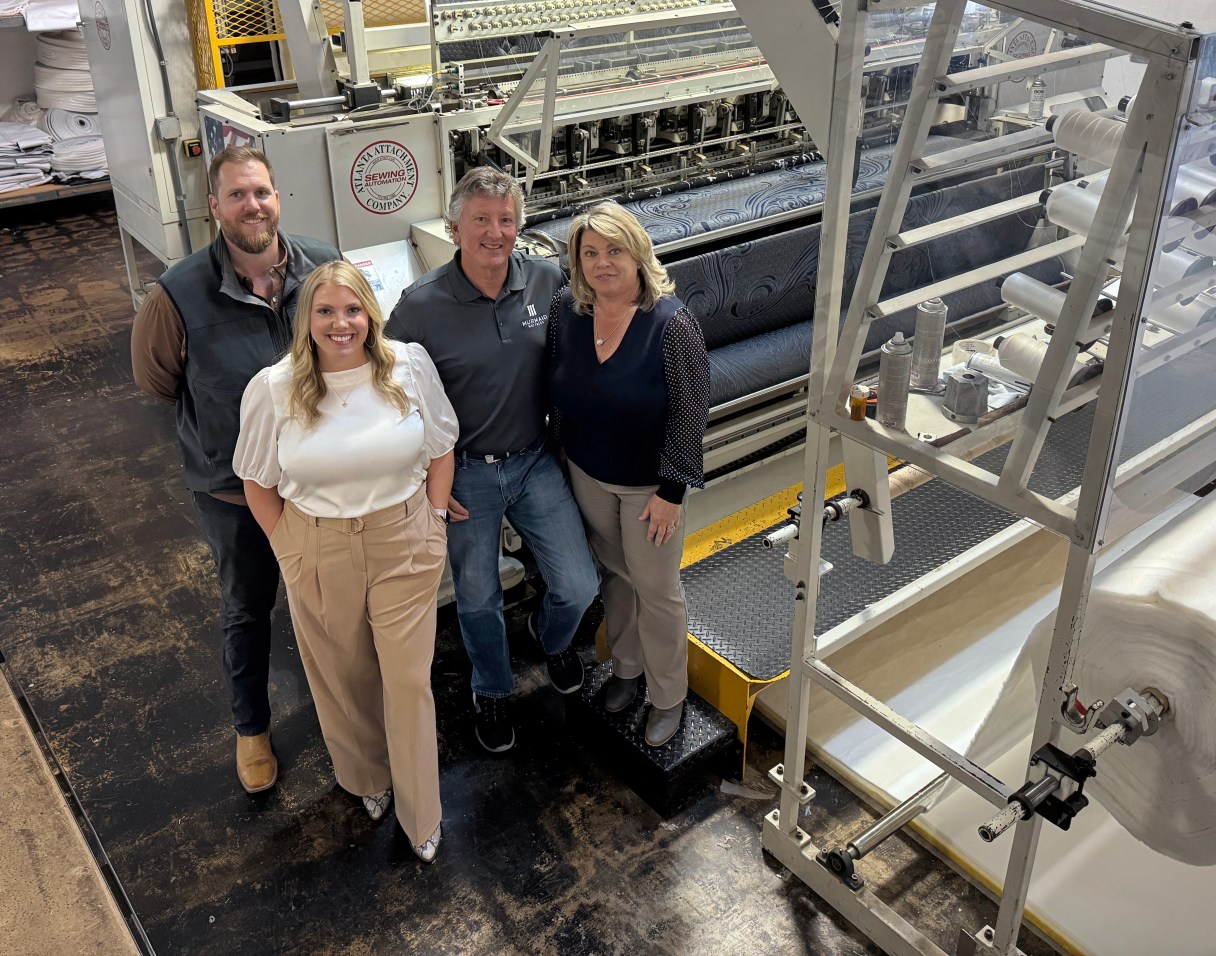
When Roger Pickett, owner of MurMaid Mattress, started thinking about retirement, he had a problem. He didn’t have anyone lined up to take over the business.
He’s not alone. It’s a common challenge for many business owners. And it’s one that can tank a company’s future.
Still, when we get caught up in the day-to-day grind, looking to the future isn’t always easy.
“Succession planning is not only important, but absolutely vital for any size company,” said Steven Layne, associate lecturer in management at the University of Tennessee at Chattanooga. “This isn’t a theoretical problem. It’s real.”
Before joining UTC, Layne spent 40 years working with large and small organizations, consulting across a range of industries including manufacturing, finance, and health care. Again and again, he watched companies face the same issue: the visionary founder wanted to step down in a few years, with no clear successor prepared to take over the position.
So, if succession planning is so essential, why is it problematic for so many companies? There are plenty of reasons, Layne said.
Part of it is timing. The decision to retire or step down usually comes on gradually, with no stand-out moment about when the time is right. But more often, he believes, it comes down to how easily we get buried in the chaos of our daily lives.
“There are so many things demanding our time and attention. So many fires to put out,” he said. “Planning for the future keeps getting bumped to tomorrow, and then tomorrow turns into weeks or months.”
But when succession planning is done well, it pays off. In the short term, it keeps a company running smoothly. There’s no panic or major disruption — and that continuity matters.
Over time, it helps preserve a company’s momentum. Employees don’t lose focus or hope, and the company is able to keep moving forward.
Layne is also an advocate for promoting from within. It’s good for the team, he said. It creates excitement and gives employees something to work toward. It also builds discipline into the organization by encouraging leaders to identify and grow talent internally.
And it’s less risky. With a solid succession plan, companies aren’t suddenly scrambling to hire someone from the outside who doesn’t know the team or culture.
Next generation
For 35 years, Roger and Cindy Pickett have run their second-generation business, MurMaid Mattress. But until recently, they weren’t sure how — or if — they’d be able to transition into retirement, or what would become of one of Chattanooga’s longest-running mattress makers.
The business was originally founded in 1979 by Joy and Elmer Murray, Roger Pickett’s mother and stepfather. Elmer, who had worked in the furniture industry, got his start by buying used machinery and making his own products, which he labeled “Murray Made.”
The Picketts took over the business in the 1990s, but for years, neither of their daughters showed much interest in taking over.
As retirement started to feel more real, Roger decided to make one final pitch to his youngest daughter and son-in-law, Kristen and Taylor Davis: “I told them, ‘If you have any interest, now’s the time.'”
Both Kristen and Taylor were working as collegiate coaches and living in San Antonio, Texas, at the time. Together, they decided it was time to head back to Chattanooga.
For Kristen Davis, she realized this was more than just a career opportunity — it was a chance to raise her kids in the same community where she grew up.
Today, the couple are several years into what will be a 10-year plan to take over ownership of her family’s business. She is focused on retail and marketing, while her husband runs the operations of the factory and delivery departments.
“The first five years are all about learning,” said Roger Pickett. “After that, hopefully Cindy and I can step back a little. We’ve got an RV, and a condo in Florida, and four grandchildren to keep us busy.”
Kristen Davis said the biggest lesson she’s learned working with her parents over the years is that “your people and customers always come first.” MurMaid has several employees who have been with the company for more than two decades, and that’s a tradition she wants to preserve.
She’s also come to understand how a small business like MurMaid can make lasting change in the local community.
“I’ve always had a mattress to sleep on without thinking about it. But when we get calls from people whose kids are sleeping on the floor, that’s what matters to me — being able to give back,” she said. “If we’re successful and the community supports us, we can pour that support right back into them.”
For what it’s worth
According to Kristin Bell, a financial planner with Simon Quick Advisors, one of the biggest reasons to start succession planning early is simple: to make sure you’re able to sell your business for what it’s actually worth.
She often recommends working with an outsourced CFO prior to engaging an investment banker, someone who can help the business owner address issues that could be roadblocks for a potential buyer, helping him or her address leadership issues and improve financial processes, internal controls, and reporting systems.
“That kind of reality check is important,” she said. “It helps to have someone who can be more objective and help you take the business to the next level.”
“If you don’t plan ahead, you may end up disappointed. … A lot of owners overestimate their business’s value because they haven’t built out the right team or put systems in place.
In fact, Bell recommends assembling a full team. Along with a fiduciary financial advisor like Simon Quick Advisors, who is advising you on how to build and steward multi-generational wealth, business owners can benefit from regular advice from a tax professional, an estate planning attorney, and a business consultant.
If a business is being passed to the next generation, Bell suggests that long-term training and planning become even more crucial. Family relationships can complicate business dynamics if both family and non-family members are involved in the business. Open communication about succession planning with key stakeholders is important, so that everyone is on the same page. Also, if one child is involved in the company and others aren’t, dividing assets fairly can be tricky. In those cases, Bell recommends working with a trusted estate planning attorney to come up with a plan.
“If your net worth is — or will be — more than $13.99 million as a single individual, or $27.98 million as a married couple, after selling your business, your estate may be subject to federal estate taxes,” she said. “In that case, it’s important to consider transferring some of your business ownership into trusts before signing any letter of intent to sell. By doing so early, you can take advantage of valuation discounts and other planning strategies.”
Ideally, that process should begin several years ahead of a potential sale. Without proactive planning, up to 40% of the portion of your estate that exceeds the exemption amounts could end up going to the government — instead of to the people and charitable causes you care about. It’s a good problem to have, she said, but one that needs to be considered nonetheless.
And she offers one final point: The Tax Cuts and Jobs Act (TCJA) is set to expire on December 31, 2025. If no further action is taken by Congress, the federal estate tax exemption will revert to an estimated $7 million per individual (and $14 million for a married couple) in 2026, cutting the current exemption in half, affecting far more individuals and families, and highlighting the need to consider making gifts today to utilize the current and historically high exemption levels.
* Call of the mountains: East Tennessee lures seniors in “silver tsunami”