
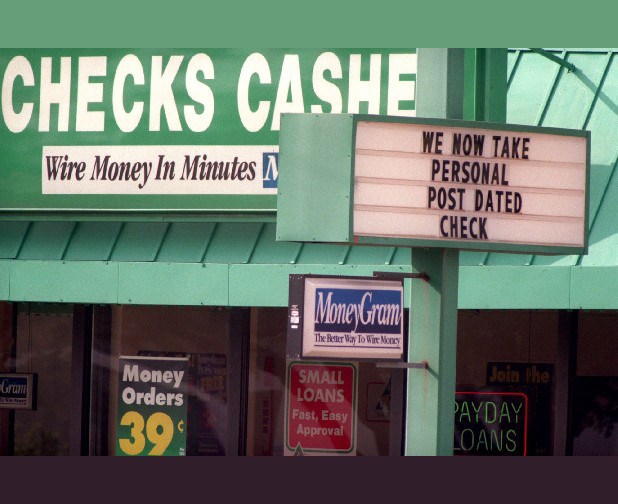
 A payday loan outlet is shown in Baton Rouge, La.
RELATED STORY
Letter stymies payday empire of Chattanooga’s Carey Brown
WHAT’S A PAYDAY LOAN?• A payday loan is a short-term, unsecured, high-interest loan.• In Tennessee, lenders can charge $15 for a $100 loan.• The loan is typically due within two weeks, or on the next payday. Hence the name payday loan.• If borrowers pay back the loan immediately, it can be a good way to avoid missing a car or a house payment.• But many borrowers let the loans roll over, only paying the interest and penalties and generating “churn,” which is how lenders make much of their money.• Many lenders prefer it this way, leaving the originally borrowed amount in the account and only debiting the interest every two weeks.• Lenders say they must charge the high interest rates because the high-risk borrowers are typically operating on the margins of society and outside traditional banking systems.• Opponents say the system traps its victims in a cycle of debt that leaves them worse off than when they started.• Recent actions by regulators have cut off some payday lenders’ ability to reach into consumers’ bank accounts as punishment for those lenders ignoring state limits on interest rates.Source: Center for Responsible Lending, State of New York, news reports
In a parallel to the 1970s-era battle over the legal right of Indian tribes to open casinos in contravention of state laws, a new generation of online payday lenders are now suing for the same type of immunity from state lending regulations, hoping to dodge rules limiting interest rates.
“This is a straightforward case that is about the real-world importance of Native American sovereign rights,” said David Bernick, an attorney working for two tribes to stop regulators in their tracks.
Recent actions by the states have challenged tribes’ ability to flout lending laws by leaning on the banks that control the nationwide banking network to choke off payday lenders’ ability to electronically deposit and withdraw money from customers’ accounts.